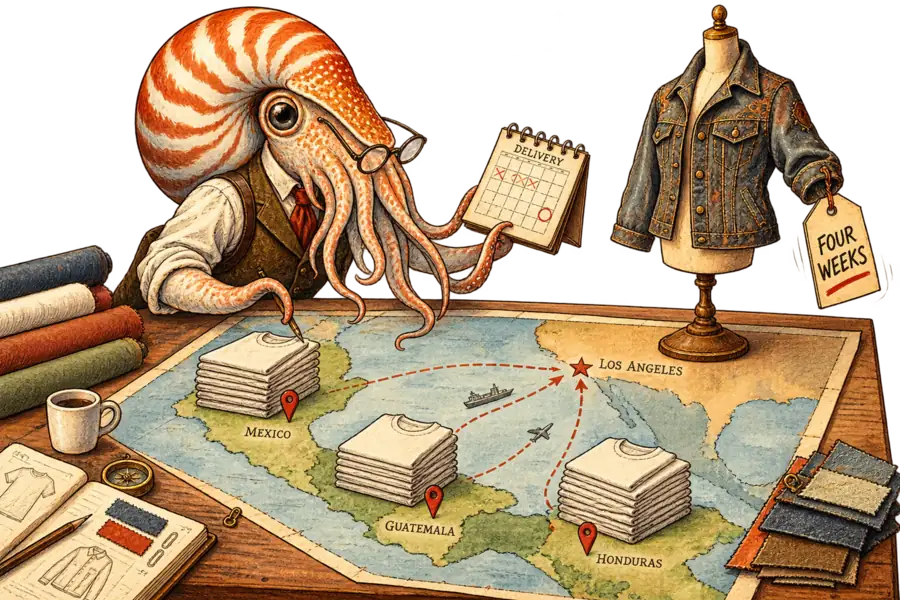
Nearshoring Took the T-Shirts. Los Angeles Sells the Four Weeks.
Nearshoring has become the default sourcing architecture rather than a crisis hedge, and it absorbed only the simplest categories. What survives in Los Angeles — pattern making, washing, finishing at low minimums — is no longer a cost problem but a scarce option on deciding late.
Admiral Neritus Vale
Only about 10 percent of US fashion companies name “Made in the USA” as a response to tariffs. That figure, from the 2026 USFIA benchmarking study run by Sheng Lu and Emilie Delaye at the University of Delaware, is the strongest available evidence that the current bidding for Los Angeles factory time has nothing to do with reshoring. Brands willing to pay a domestic premium are buying speed: a four-week reorder instead of a twelve-week one, and nearshoring is what turned that trade into a priced one.
Nearshoring stopped functioning as a pure hedge this year and started looking like the default option, though the survey behind that shift is careful to call it a slight increase rather than a break. Seventy-six percent of the executives surveyed sourced from CAFTA-DR countries in 2026, up from 64 percent the year before, and the same respondents are now favoring supplier consolidation over expansion — few are adding new vendors or new countries. Lu reads this as a move from geographic expansion to network optimisation, a careful way of saying the search phase is over. A company that has stopped searching has committed to an architecture. FashionUnited’s 14 August survey of the practice describes that architecture in operation: distant Asian plants hold the predictable volume, regional plants absorb the volatility.
What nearshoring has not absorbed is difficulty. Sixty-seven percent of the companies sourcing in CAFTA-DR buy t-shirts there, 33 percent buy activewear and athleisure, and 27 percent buy bottoms; these are independent adoption rates, not shares of a single pie, since most respondents source more than one category. The Mexican mix skews the same way. That pattern likely reflects rules of origin as much as ambition: CAFTA-DR’s duty-free terms favor garments cut and sewn from regional or U.S. yarn, which rewards knit commodity basics over anything needing a specialty pattern or finish. A garment needing a graded pattern on an unfamiliar block, a specialty wash and three sequential finishing steps does not appear on that list and will not appear soon. Nearshoring took the volume and left the craft where it was.
The difficult garment therefore goes to Los Angeles, where Glossy’s Zofia Zwieglinska reported on 14 August that roughly 17,000 apparel manufacturing workers remain, citing Bureau of Labor Statistics data.
That is about 23 percent of national apparel manufacturing employment, a share that says more about the national number than the local one: American apparel jobs have shrunk to the point where one metro area holds nearly a quarter of what’s left. What remains in Los Angeles is adjacency rather than scale: pattern makers, sewers, wash houses, dye houses and finishers sitting close enough together that a brand can run those stages in parallel instead of in sequence. That compression is the product, and it is the one input that cannot be containerised.
That workforce is also fragile. Immigration raids across the Fashion District in June 2025 led to worker absences, reduced production and delayed shipments, per Glossy’s reporting — a reminder that the compressed calendar these brands are buying depends on people who can vanish from the shop floor without warning.
The founders are explicit about what they are buying, and it is not cloth. Rat Boi’s founder, Alexa Coughlin, told Glossy that its Los Angeles premium runs 30 to 50 percent over overseas quotes, depending on the garment; a bolero set restocked in four weeks, against at least twelve overseas. “We can meet demand instead of watching it pass, and we don’t have to guess a season out, overproduce and sit on dead inventory hoping it sells,” she said. Mayanna opens styles at around 200 pieces where its overseas factories wanted a thousand. Neither is a statement about quality or provenance; both describe the same purchase, which is the right to commit later and smaller. Rat Boi’s planner, Emma Treibatch, named the mechanism in terms no software vendor would have chosen: “Planning becomes way less ‘crystal ball’ and way more ‘paying attention to what’s happening right now.’”
{{generate: A narrow Los Angeles cutting-room corridor seen end-on, with three work stations running at once rather than in a line: a pattern maker bent over a table of paper blocks, a sewer at a machine, and a wash-house drum turning behind them. Above each station hangs an identical wall clock showing the same time. Taped to the brick wall is a handwritten sign reading CUT MAKE TRIM with the words struck through and CALENDAR lettered underneath. Mood: parallel work being sold by the hour.}}
Set that premium against the retail price and it stops looking like a cost problem. Will Tendler, whose label retails between $225 and $1,450, told Glossy that overseas production could run as much as $20 less per unit, and warned that “if you just focus on the per-unit costs, you’re oversimplifying the economics in a way that could severely hurt your brand.” A spread that size, at that price, is not a sourcing decision. It is a rounding error against a single markdown cycle on goods nobody ordered. Tendler is precise about what the money actually buys: “There’s incredible pattern makers, incredible sewers, the wash houses.”
The obvious reading is that tariffs and freight risk pushed these brands home, and that is at best half right. If duty-driven reshoring were happening at scale, it should show up first among the largest importers, the companies most exposed to tariffs and most motivated to escape them. Lu’s own summary finds little evidence that higher tariffs have encouraged large-scale reshoring of apparel production to the United States. The companies bidding up Los Angeles factory time are small, growth-stage and margin-sensitive, the profile least able to absorb a domestic premium and most tempted by a duty-free Guatemalan quote. They pay it anyway. Their binding constraint is the gap between noticing demand and being able to serve it, and no tariff schedule touches that.
We argued in July that wholesale buyers had begun writing free options on their vendors’ warehouses, cutting pre-book depth while assuming at-once stock would somehow exist. The Los Angeles market is the same instrument one layer down the chain, and it is the layer where someone is finally collecting. A brand that can reorder domestically in four weeks no longer needs to speculatively build the at-once unit the previous autumn. The factory making that possible has sold an option and charged a premium for it without ever using the word. Its customers file the premium under cost of goods.
The strongest case against this reading is that Los Angeles is too small to be a market at all. A workforce that size, opening runs in the low hundreds, and a customer list of labels most sourcing directors have never heard of describe a boutique rather than an asset class. For the argument to fail, one condition would have to hold: the nearshore region would need to reproduce the speed and not merely the proximity. That is not impossible — Guatemala and Mexico have every incentive to try. The obstacle is not capital equipment, since a wash line can be bought inside a year, but a bench of pattern makers who can grade an unfamiliar block on the first attempt, and a bench like that is a labour market rebuilding on a slower clock than any factory.
Los Angeles factories sell hours, units and yardage, which is the only vocabulary the industry ever gave them. It guarantees they are measured against Guatemala on unit cost, a comparison they lose on every line and will keep losing. What they hold instead is a compressed calendar, and the price of a compressed calendar is set by how few suppliers can offer one. If nearshoring holds as the default architecture and regional capability stays concentrated in knit basics, the shops still standing in Los Angeles will own something genuinely scarce. Whether they charge for it or keep quoting cut-make-trim is a decision rather than a market condition, and it is theirs to make.