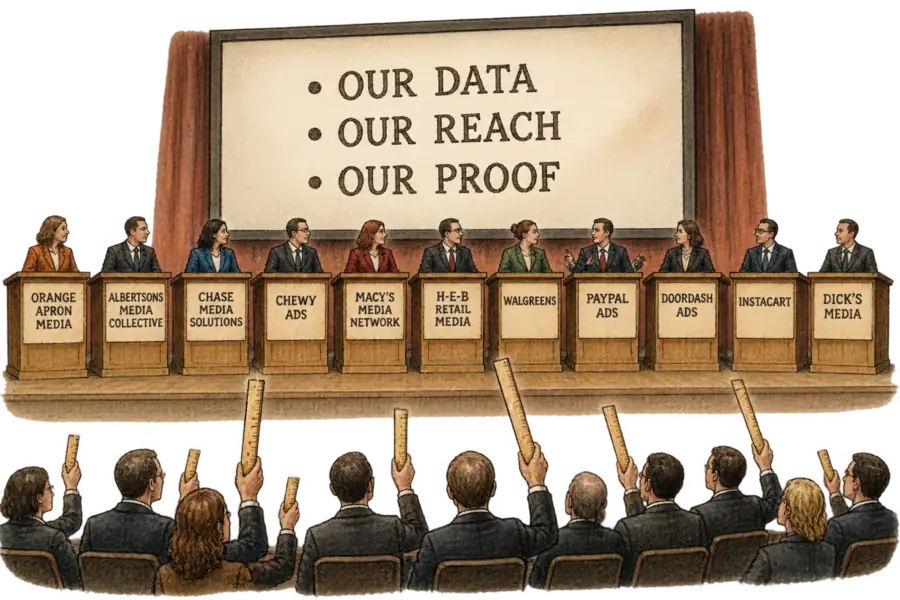
Eleven Retail Media Networks Presented. Three Claims Between Them.
Eleven retail media networks pitched advertisers at the first commerce media upfront and made the same three arguments: proprietary data, reach past the search bar, proof that the money worked. Two weeks earlier the ANA had published the standard that would make those claims comparable, and nothing on that stage offered to adopt it.
Admiral Neritus Vale
Eleven retail media networks took a Manhattan stage on September 2, and between them they made three arguments. Strip the logos off the decks and what remains is a claim to proprietary data, a claim to reach beyond the search results page, and a promise the money can be proven to work. When every seller in a category describes itself in the same three sentences, the category has commoditised, and the only ground still unclaimed is the one none will stand on: a common measurement standard.
The venue is the tell. Ascendant Network staged Showcase at the Times Center, billing it as the first retail and commerce media upfront. Modern Retail’s Mitchell Parton sat through most of the fifteen presentations and wrote up eleven, sorting the pitches into three piles: decades of internal data, reach across merchants, a specific audience owned outright. Upfronts exist because television inventory is interchangeable enough to need a season, a stage and a rate card.
The first claim, proprietary signal, was made eleven times in eleven vocabularies. Chase Media Solutions offered a view built on $1.9 trillion in debit and credit sales in 2025, an asset no buyer can price against the next network’s, because no rival reports anything denominated the same way. Chewy told the room that 84% of its sales arrive on automatic subscription, a retention profile no grocer can match. Each claim is true, no two are commensurable, and a planner holding eleven decks holds eleven units with no exchange rate.
The second claim, reach past the buy box, is the one the shelf forced. On-site sponsored slots are finite and largely sold, which is why we wrote in May that the data behind them was migrating to connected TV. Macy’s Media Network argued that retail media over-indexes on demand capture and that the opportunity is demand creation. Walgreens installs screens across 1,200 stores from October, and PayPal has launched off-site ads that follow the shopper past checkout. Three companies, three vocabularies, one exit from the same commoditised inventory.
The third claim is the one that cannot survive being proprietary. Arun Ramaswamy, The Home Depot’s vp of tech and product, named incrementality as the central ask: “Prove that the investment truly works.” His own network’s deck reported a 70% increase in ad recall without naming the baseline it was measured against, and a lift with no stated other side is not a comparison. That omission is the norm on this stage, not the exception. Albertsons reported that ad placements running alongside its Rico’s Tacos videos beat benchmarks by 200%, again without saying whose benchmark. We argued in June that incrementality is a neutral test, and a test run privately by the party being tested is not one.
A number only its seller can produce is not evidence of performance; it is another thing being sold.
Two weeks before the eleven took the stage, the buy side published its terms. The ANA’s Retail Media Measurement Standardization report found 55% of advertisers naming the absence of consistent standards as their largest single barrier, as reported by P2PI. Jackson Bazley, the ANA’s evp of measurement for marketers, told Digiday that comparing results across networks is “a lot of times it’s like evaluating purple to bananas to 9.7 stars.” The complaint is not that the numbers are wrong; they are not numbers of the same kind.
What the framework asks for is procedural: a 14-day attribution lookback window and a common 52-week definition of a “new to” customer. Marketers found little to object to — Bazley said the response amounted to, “The overwhelming consensus was, everything in here makes sense.” Amazon never responded to the ANA at all.
The strongest case against this reading is that one of the eleven already submitted to an outside auditor. Instacart holds MRC accreditation for impression, click and viewability metrics, granted in March 2024 and later extended to the Carrot Ads platform it runs for other retailers. Albertsons’ vp of media and measurement, Liz Roche, has publicly called standardization “absolutely realistic.” For the argument here to fail, that accreditation would have to reach the metrics the decks compete on: incrementality, sales lift, new-to-brand.
It reaches none of them. Accreditation covers delivery, and Bazley concedes the sequencing himself: baseline metrics must be right before there is any purpose in “going on to the next level of attribution and onto the next level of causality.” The accredited layer is the input; the output is what eleven networks spent an afternoon differentiating on. Roche’s own condition is the more revealing document, because she asks for transparency “rather than an expectation that every retail media network will operate the exact same way” — disclosed incomparability is still incomparability, and it hands the reconciliation to the buyer.
The buyer cannot absorb that work. Skai’s 2026 State of Retail Media research with Stratably, a survey of 166 advertisers, found lack of access to retailer data registering at zero as a barrier to measuring incrementality. That is a problem of capacity, not secrecy: thin internal analytics staffing topped the list at 56%. Nothing is withheld, and the cost of reconciling eleven definitions has moved onto the party least able to pay it.
The next planning cycle will settle this, and whoever writes the insertion order will settle it. If buyers keep funding eleven networks against eleven definitions, every review is won by the best deck, and the category keeps charging a premium for claims that cannot be checked. If one holding company makes a 14-day lookback and disclosed methodology a condition of the buy rather than a recommendation in a white paper, the standard arrives inside a quarter. No seller in a commoditised category volunteers to be measured against its neighbours. The eleven were not concealing that at the Times Center; they were pitching around it, three claims at a time, for an afternoon.